Releases

Federated Credit Risk Models

Federated Credit Risk Models

Reading Time: 4 min.

The motivation for federated credit risk models

Federated learning is a machine learning technique that is receiving increased attention in diverse data driven application domains that have data privacy concerns. The essence of the concept is to train algorithms across decentralized servers, each holding their own local data samples, hence without the need to exchange potentially sensitive information. The construction of a common model is achieved through the exchange of derived data (gradients, parameters, weights etc). This design stands in contrast to traditional model estimation where all data reside (or are brought into one computational environment).
Overview of the Julia-Python-R Universe

Overview of the Julia-Python-R Universe

We introduce a side-by-side review of the main open source ecosystems supporting the Data Science domain: Julia, Python, R, the trio sometimes abbreviated as Jupyter

Reading Time: 3 min.

Overview of the Julia-Python-R Universe

A new Open Risk Manual entry offers a side-by-side review of the main open source ecosystems supporting the Data Science domain: Julia, Python, R, sometimes abbreviated as Jupyter.

Motivation

A large component of Quantitative Risk Management relies on data processing and quantitative tools ( aka Data Science ). In recent years open source software targeting Data Science finds increased adoption in diverse applications. The overview of the Julia-Python-R Universe article is a side by side comparison of a wide range of aspects of Python, Julia and R language ecosystems.

Data Quality and Exploratory Data Analysis using Python

Data Quality and Exploratory Data Analysis using Python

Reading Time: 0 min.

Data Quality and Exploratory Data Analysis using Python

In two new Open Risk Academy courses we figure step by step how to use python to work to review risk data from a data quality perspective and how to perform exploratory data analysis with pandas, seaborn and statsmodels:

Open Source Securitisation

Open Source Securitisation

Reading Time: 5 min.

Open Source Securitisation

Motivation

After the Great Financial Crisis securitisation has become the poster child of a financial product exhibiting complexity and opaqueness. The issues and lessons learned post-crisis were many, involving all aspects of the securitisation process, from the nature and quality of the underlying assets, the incentives of the various agents involved and the ability of investors to analyze the products they invested in. While the most egregious complications involved various types of re-securitisation and/or the interplay of structured credit derivatives undoubtedly even vanilla securitisation structure has a considerable amount of business logic.

Visualization of large scale economic data sets

Visualization of large scale economic data sets

Reading Time: 3 min.

Visualization of large scale economic data sets

Economic data are increasingly being aggregated and disseminated by Statistics Agencies and Central Banks using modern API’s (application programming interfaces) which enable unprecedented accessibility to wider audiences. In turn the availability of relevant information enables more informed decision-making by a variety of actors in both public and private sectors. An excellent example of such a modern facility is the European Central Bank’s Statistical Data Warehouse (SDW), an online economic data repository that provides features to access, find, compare, download and share the ECB’s published statistical information.

Machine learning approaches to synthetic credit data

Machine learning approaches to synthetic credit data

Reading Time: 9 min.

The challenge with historical credit data

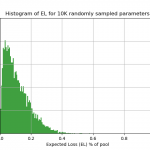
Historical credit data are vital for a host of credit portfolio management activities: Starting with assessment of the performance of different types of credits and all the way to the construction of sophisticated credit risk models. Such is the importance of data inputs that for risk models impacting significant decision-making / external reporting there are even prescribed minimum requirements for the type and quality of necessary historical credit data.

Stressing Transition Matrices

Stressing Transition Matrices

Reading Time: 1 min.

Release of version 0.4.1 of the transitionMatrix package focuses on stressing transition matrices

Further building the open source OpenCPM toolkit this release of transitionMatrix features:

  1. Feature: Added functionality for conditioning multi-period transition matrices
  2. Training: Example calculation and visualization of conditional matrices
  3. Datasets: State space description and CGS mappings for top-6 credit rating agencies
Release 0.4 of transitionMatrix adds Aalen-Johansen estimators

Release 0.4 of transitionMatrix adds Aalen-Johansen estimators

Reading Time: 0 min.

Release of version 0.4 of the transitionMatrix package

Further building the open source OpenCPM toolkit this release of transitionMatrix features:

  1. Feature: Added Aalen-Johansen Duration Estimator
  2. Documentation: Major overhaul of documentation, now targeting ReadTheDocs distribution
  3. Training: Streamlining of all examples
  4. Installation: Pypi and wheel installation options
  5. Datasets: Synthetic Datasets in long format

Enjoy!

NACE Economic Activity Pictograms

NACE Economic Activity Pictograms

Reading Time: 2 min.

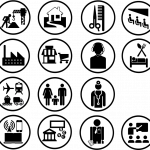
Representing economic activity using pictograms

Visualization can produce significant new insights when applied to quantitative data. It is currently undergoing a renaissance that mirrors other developments in computing and data science. Sophisticated open source libraries such as d3.js or matplotlib, to name but a couple, are enabling an ever wider range of users to distill valuable information from the avalanche of data being produced.

Version 0.2 of the Open Risk API incorporates the standardized EBA portfolio data templates

Version 0.2 of the Open Risk API incorporates the standardized EBA portfolio data templates

Reading Time: 2 min.

Extending the Open Risk API to include the EBA Portfolio Data Templates

The Open Risk API provides a mechanism to integrate arbitrary collections of risk data and risk modelling resources in the context of assessing and managing financial risk. It is based on two key technologies of the modern Web, RESTful architectures and Semantic Data.

Credit Portfolio Management in the IFRS 9 / CECL and Stress Testing Era

Credit Portfolio Management in the IFRS 9 / CECL and Stress Testing Era

Reading Time: 3 min.

Credit Portfolio Management in the IFRS 9 / CECL and Stress Testing Era

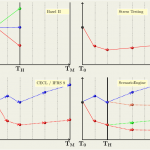
The post-crisis world presents portfolio managers with the significant challenge to assimilate in day-to-day management the variety of conceptual frameworks now simultaneously applicable in the assessment of portfolio credit risk:

  • The first major strand is the widespread application of regulatory stress testing methodologies in the estimation of regulatory risk capital requirements
  • The second major strand is the introduction of new accounting standards (IFRS 9 / CECL) for the measurement and disclosure of expected credit losses While both Regulatory Stress Testing and IFRS 9 / CECL accounting require investment in analytic capabilities and provide unique new insights, both are aimed at satisfying evolving prudential or investor disclosure requirements. Neither is designed to help credit portfolio managers analyse and steer their portfolios in the bottom-up fashion that is an essential part their mandate.

The above developments are overlaid into pre-existing conceptual and practical frameworks such as

A Risk Agnostic Approach to European Safe Bonds (ESBies) Tranching

A Risk Agnostic Approach to European Safe Bonds (ESBies) Tranching

Reading Time: 7 min.

What are European Safe Bonds?

While the creation of the eurozone was a landmark of the European integration process, the financial crisis highlighted that the eurozone remains an incomplete design which can lead to unpredictable and adverse situations in the event of a (the) next major crisis. One of the key such incompleteness features of the current eurozone architecture is that it does not have a truly risk-free (safe) euro debt instrument: one that continues being serviced (avoids a default event) at virtually any point in time and state of the world, no matter how severe.

Release of version 0.3 of the Concentration Library

Release of version 0.3 of the Concentration Library

Reading Time: 0 min.

Release of version 0.3 of the ConcentrationMetrics Library

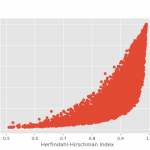
Further building out the OpenCPM set of tools, we release version 0.3 of the ConcentrationMetrics Library. This python library for the computation of various concentration, diversification and inequality indices.

The below list provides documentation URL’s for each one of the implemented indexes

OpenNPL Database

OpenNPL Database

Reading Time: 2 min.

Motivation for Building an open source database based on EBA’s Standardized NPL Templates

In an insightful recent piece, “Overcoming non-performing loan market failures with transaction platforms”, Fell et al. dug deeply into the market failures that help perpetuate the Non-performing loan (NPL) problem. They highlight, in particular, information asymmetries and the attendant costs of valuing NPL portfolios as key obstacles. In the same wavelength, the European Banking Authority published standardized NPL data templates as a step towards reducing the obstacles that prevent the reduction of NPL’s.

Transition Matrix Library First Release

Transition Matrix Library First Release

Reading Time: 2 min.

Transition Matrix Library First Release

Open Risk released version 0.1 of the Transition Matrix Library

Motivation

State transition phenomena where a system exhibits stochastic (random) migration between well-defined discrete states ( see picture below for an illustration) are very common in a variety of fields. Depending on the precise specification and modelling assumptions they may go under the name of multi-state models, Markov chain models or state-space models.

Loan Level Templates Using Python

Loan Level Templates Using Python

Loan Level Templates Using Python

Reading Time: 0 min.

Loan Level Templates Using Python

In this Open Risk Academy course we figure step by step how to use python to work with Loan Level Templates, using the ECB SME template as an example.

  • Overview of the loan level template
  • Manipulating spreadsheets with Python
  • The Python Dictionary
  • Organization of Portfolio Data
  • Generating Test Portfolios

Get an Open Risk Academy account and get started with the course here

How much digital bank can we fit in a 50 euro bill?

How much digital bank can we fit in a 50 euro bill?

Reading Time: 2 min.

How much digital bank can we fit in a 50 euro bill?

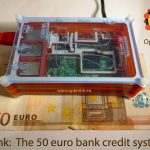
Much has been said about the impact of Big Data and high-end GPU Computing on the provision of digital financial services. At Open Risk we wanted to explore the boundary of what is possible at the diametrically opposite end of the cost spectrum:

What is the_absolutely minimum_cost for providing digital financial services? . In this post we begin the journey of finding out the answer to that question and it promises to be fascinating!

Fintech Risk Events

Fintech Risk Events

Reading Time: 1 min.

Fintech Risk Events

Fintech Risk Events is an open catalog of observed and publicized operational failures of fintech business models. The catalog aims to document, in due course, such events reasonably accurately, to allow risk managers understand the ( potentially new) vulnerabilities of new financial services models.

Scope

The scope of the operational risk database is Fintech companies. By that we mean newly established financial services providers that operate exclusively via new (digital) platforms and are (mostly) unregulated. The fintech sector is distinct from established financial services firms that operate with a mix of technology platforms and are (mostly) regulated.